PA Homebuyer’s Guide to PHFA Loans
Posted on
Buying a home for the first time can come with a long list of questions, among them, how much do you need for a down payment, and what credit score is enough?
If you're buying a home in Pennsylvania, you may have heard of a PHFA loan. PHFA programs are designed to make homeownership more accessible to eligible Pennsylvania buyers, including those who may need a lower down payment or assistance with upfront costs. Here's what prospective homebuyers in Columbia, Montour, Northumberland, Lycoming, and Clinton counties should know.
What Is a PHFA Loan?
PHFA stands for the Pennsylvania Housing Finance Agency, a state agency that helps make homeownership more attainable for qualified Keystone State residents.
One important distinction: PHFA is not a lender itself. Instead, it works with a network of participating lenders that originate and close mortgages under PHFA programs. That means you can work with a local lender, such as Journey Bank, to explore whether a PHFA mortgage may be a good fit for you.
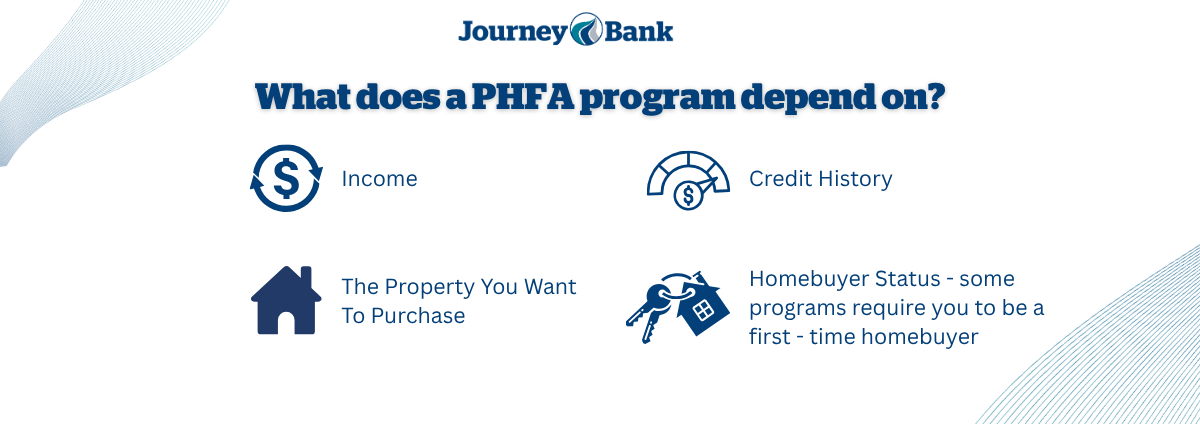
The specific program available to you depends on your income, credit history, the property you want to purchase, and whether you meet other requirements.
Why a PHFA Loan Might Be Right for You
If saving for a traditional down payment is one of your biggest barriers to homeownership, a PHFA loan can be worth exploring.
Depending on the program, buyers may also qualify for assistance with down payment and closing costs. Learn more about Journey Bank’s PHFA and FHA mortgage options.
Credit requirements may also be more accessible than buyers expect, although minimum scores vary by program and whether assistance is included.
Despite the common phrase “PHFA first-time home buyer,” not every PHFA loan requires you to be a first-time homebuyer. That makes it worthwhile to talk with a lender before assuming you do or don’t qualify.
Do You Qualify?
PHFA loan eligibility depends on several factors, including whether you meet PHFA first-time home buyer requirements, your income, and your credit history:
First-time homebuyer status: Some PHFA programs require you to be a first-time buyer. PHFA defines a first-time homebuyer as someone who has not owned a principal residence during the previous three years. There are exceptions for certain buyers, including eligible veterans and buyers purchasing homes in targeted areas. Other PHFA programs do not have a first-time buyer requirement.
Household income: Many PHFA programs have household income limits, and those limits can vary by program and by county. A PHFA loan in Columbia County may carry different income limits than a PHFA loan in Northumberland County, so it's worth confirming the figures that apply to your specific address with a lender.
Credit history: Your credit profile is another factor. Minimum credit thresholds can vary by program. For example, some PHFA programs paired with assistance have specific minimum FICO scores.
Homebuyer education: Homebuyer education is part of what's needed for PHFA home purchase loans, though how it's completed may depend on the loan and the borrower's credit score. PHFA also works with approved homebuyer counseling agencies.
Property requirements: The home generally needs to meet the standards of the particular mortgage program. Your lender can explain which property types and locations qualify.
Because eligibility varies by program, it's best to confirm the details that apply to you with a lender rather than relying on a general PHFA first-time home buyer checklist.
PHFA Down Payment Assistance and Closing Cost Help
One of the biggest challenges for first-time buyers isn't necessarily qualifying for a mortgage. It can be coming up with enough cash to cover the down payment and closing costs.
Eligible buyers may have access to PHFA assistance programs that help cover some of these upfront costs. Assistance may be structured as a separate loan with its own repayment terms. Your lender can explain how the available options work and what obligations come with them.
PHFA assistance may be paired with certain first mortgages to help eligible buyers with down payments and closing costs.
Availability depends on the specific program and current funding, so assistance isn't guaranteed simply because you qualify for a PHFA mortgage.
This is one reason it can be helpful to speak with a local mortgage lender early in the process. A lender can look at your finances and help determine whether you may qualify for a PHFA loan and related assistance.
How the Process Works with Journey Bank
If you're wondering how a PHFA loan works from start to finish, the process is similar to applying for other mortgages, with additional program requirements along the way.
1. Talk with a local mortgage lender
Start by discussing your goals, income, savings, and credit history with a participating lender. Journey Bank's mortgage team can help you explore available home loan options and determine whether a PHFA program may be appropriate for your situation. Learn more about Journey Bank’s home mortgage options before getting started.
2. Get prequalified
Your lender can review your financial information and give you a better idea of how much you may be able to borrow. This can help you establish a realistic homebuying budget before you start making offers. That context can also help you shop with greater confidence. You can also use Journey Bank's mortgage calculators to get a general sense of potential payments and affordability.
3. Complete required homebuyer education
You'll also need to complete the homebuyer education required for your PHFA loan. How that education is completed can depend on your loan and credit profile.
PHFA encourages buyers to seek counseling early, particularly before signing a sales agreement.
4. Find a qualifying home
Once you know your budget and understand your loan options, you can shop for a home that meets the applicable program requirements.
5. Apply and move toward closing
Your Journey Bank lender will review your application and financial documentation. From there, they can explain any remaining PHFA requirements and guide the loan toward closing.
Quick Checklist: Is a PHFA Loan Right for You? A PHFA mortgage (https://phfa.org/) may be worth exploring if you answer "yes" to one or more of these questions:
● Are you planning to purchase a primary residence in Pennsylvania?
● Are you a first-time homebuyer, or do you qualify for a PHFA program that doesn't require first-time buyer status?
● Would a lower down payment make buying a home more achievable?
● Do you need help covering some of your down payment or closing costs?
● Does your household income fall within the applicable PHFA limits?
● Are you willing to complete required homebuyer education?
● Are you looking for a local lender to help you understand your options?
If you're buying a home in Central Pennsylvania, the next step is to find out what you may qualify for based on your individual circumstances. Ready to explore your options? Connect with a local Journey Bank mortgage lender to see whether a PHFA loan in Montour County or wherever you are looking could be a good fit for your homebuying goals. A lender can walk you through available programs, eligibility requirements, and the next steps toward purchasing your Pennsylvania home.